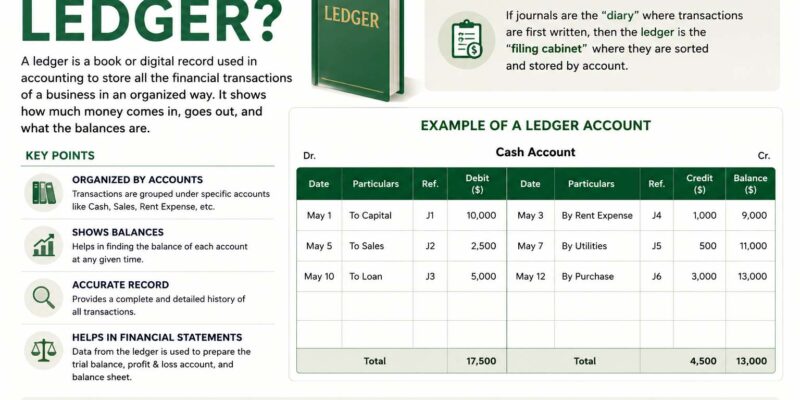
If you are wondering what is a ledger, it is a book or digital record that organizes financial transactions into specific accounts. A ledger helps businesses track income, expenses, assets, liabilities, and other financial activity. As a result, it provides an organized view of financial records and supports accurate bookkeeping.
Modern businesses often maintain ledgers through accounting software, although some organizations still use traditional accounting books. The format may change, but the main purpose remains the same: grouping financial transactions into accounts so people can review and understand financial activity.
For example, a small business owner can use accounting records to monitor daily expenses and income. A larger company may use detailed ledger accounts when preparing financial statements. Businesses learning what is a business license may also need organized financial records as part of managing their operations.
What Is a General Ledger?
A general ledger is the main accounting record that organizes a business’s financial transactions by account. It can contain information related to sales, purchases, payroll, expenses, assets, liabilities, equity, and other financial activities.
Accountants typically organize general ledger accounts into categories such as assets, liabilities, equity, revenue, and expenses. When a transaction occurs, the accounting system records its effect in the appropriate accounts. Therefore, businesses can use ledger information when preparing financial reports such as balance sheets and income statements.
For example, suppose a company purchases office equipment. The business records the equipment in the appropriate asset account and records the corresponding side of the transaction according to its accounting system. This approach keeps financial information organized and makes individual transactions easier to review.
A well-maintained general ledger can also help businesses identify accounting errors. By reviewing account entries regularly, owners and accountants may find missing transactions, duplicate entries, or unusual activity.
The Internal Revenue Service guidance on recording business transactions explains that businesses commonly summarize transactions in journals and ledgers. It also describes a ledger as a record organized into different accounts.
What Is a Ledger Balance?
A ledger balance generally refers to an account balance based on transactions that have been processed through a particular point in time. In banking, the ledger balance may differ from the amount currently available to spend because pending transactions, holds, or other account activity can affect available funds.
For example, a bank account may show a balance based on posted transactions while a recent card purchase remains pending. Therefore, account holders should not automatically assume that the ledger balance equals the amount they can immediately withdraw or spend.
Understanding this difference can help individuals and businesses manage cash flow more carefully. Checking both recorded and available funds can reduce the risk of spending money that remains affected by pending transactions.
Businesses also compare their accounting records with bank statements through reconciliation. During this process, they can identify missing entries, duplicate transactions, bank fees, or other differences. Regular reconciliation helps maintain accurate records and allows businesses to investigate discrepancies promptly.
What Is a Tenant Ledger?
A tenant ledger is a financial record that tracks charges, payments, deposits, credits, and balances associated with a rental agreement. Landlords and property managers use these records to maintain a clear financial history for each tenant.
A tenant ledger may include monthly rent charges, payment dates, amounts paid, late fees, security deposit information, credits, and outstanding balances. Consequently, landlords can review a tenant’s account without searching through individual receipts or payment records.
For tenants, this record can provide a useful history of payments and charges. For example, a tenant may review the ledger when checking whether a landlord correctly applied a payment or fee.
A properly maintained tenant ledger can also improve transparency between both parties. If a disagreement occurs over an outstanding balance, the landlord and tenant can review the transaction history and compare it with receipts, bank records, or other supporting documents.
Today, many property management systems maintain tenant records digitally. As a result, property managers can organize accounts for multiple rental properties more efficiently and update payment histories as transactions occur.
What Is a Rent Ledger?
A rent ledger specifically tracks rental charges and payments over a particular period. Although it closely resembles a tenant ledger, its main purpose is to provide an organized history of rent-related transactions.
A typical rent ledger may show rent due dates, amounts charged, payments received, missed or partial payments, credits, and outstanding balances. Landlords and property managers can use this information to monitor rental income and identify overdue accounts.
For instance, a landlord reviewing a lease renewal may check the rent ledger to confirm a tenant’s payment history. Likewise, a tenant may request a copy to review previous payments or clarify a disputed balance.
Keeping the record current benefits both landlords and tenants because it creates a clear transaction history. In addition, property owners who manage several rental units can use rent records to monitor payments without relying on memory or scattered receipts.
How Does a Ledger Work?
A ledger works by grouping financial transactions according to their relevant accounts. Instead of keeping every transaction in one unorganized list, an accounting system separates activity into categories that make financial information easier to understand.
For example, a business may maintain separate accounts for cash, sales revenue, rent expense, equipment, accounts payable, and other categories. When a transaction occurs, the business records its effect on the relevant accounts.
In a double-entry bookkeeping system, every transaction affects at least two accounts. For example, when a business buys equipment with cash, the equipment account increases while the cash account decreases. This structure helps keep the accounting records balanced.
Businesses may use accounting software to automate much of this process. However, the underlying principle remains the same whether someone uses software or traditional accounting books: transactions must appear in the correct accounts so the financial records remain organized.
Why Ledgers Matter in Financial Management
Ledgers play a central role in financial recordkeeping because they give businesses a structured way to organize transactions. Without organized accounts, business owners would have more difficulty understanding where money comes from, where it goes, and how different financial activities affect the company.
For someone researching partnership business examples or planning how to start a cleaning business, accurate recordkeeping can make financial management easier from the beginning. Likewise, someone exploring how to start a photography business needs a reliable system for monitoring revenue, expenses, equipment purchases, and other transactions.
Ledgers also help businesses prepare financial statements and review financial performance. Organized account records make it easier to examine revenue and expense activity over a particular period.
In addition, accurate records support transparency and accountability. Business owners and accountants can review transaction histories instead of relying on estimates or memory. Therefore, a well-maintained ledger can reduce confusion and make financial information easier to verify.
Different Types of Ledgers at a Glance
Although the general ledger is central to business accounting, the term can describe several types of financial records.
- General ledger: Organizes a business’s financial transactions across its accounts.
- Ledger balance: Shows a recorded account balance based on processed transactions at a particular point in time.
- Tenant ledger: Tracks charges, payments, credits, deposits, and balances connected with a tenant.
- Rent ledger: Focuses primarily on rent charges, payments, and outstanding rental balances.
The information recorded depends on the purpose of the ledger. However, each type shares the same basic goal: creating an organized financial record that people can review and understand.
Conclusion
Understanding what is a ledger makes it easier to understand how businesses, financial institutions, landlords, and individuals organize financial activity. In accounting, ledgers group transactions into relevant accounts and provide records that businesses can use to review their financial position.
A general ledger organizes company-wide account information, while a ledger balance helps explain the amount recorded in an account. Meanwhile, tenant and rent ledgers provide organized financial histories for rental arrangements.
Although modern software has changed how people maintain these records, the basic purpose remains straightforward: a ledger keeps financial transactions organized, traceable, and easier to review.